Restructure Debt & Protect What Matters Most
Under Chapter 13 bankruptcy—often referred to as the "wage earner's plan"—individuals and family breadwinners with regular income reorganize their financial obligations into an affordable, single monthly disbursement paid to a Chapter 13 Standing Trustee over three to five years (36 to 60 months).
Unlike Chapter 7 liquidation, Chapter 13 allows you to keep non-exempt real estate and personal assets, cure past-due mortgage delinquencies without penalty, stop vehicle repossessions, eliminate junior mortgage liens, and shield family co-signers under the 11 U.S.C. § 1301 co-debtor stay.
11 U.S.C. § 1322: The Court-Approved Repayment Plan
Federal law gives debtors the legal authority to dictate reasonable repayment terms to otherwise unyielding mortgage servicers and aggressive collection creditors.
Comprehensive Texas Asset Protection Under Chapter 13
Chapter 13 provides an ironclad shield when you own valuable real estate or vehicles with substantial equity that exceed exemption limits, or when you need court intervention to catch up on defaulted secured loans.

Cure Mortgage Arrears
If your mortgage servicer has accelerated your note or posted your property for a First Tuesday auction, Chapter 13 freezes the sale instantly and spreads missed payments interest-free over 36 to 60 consecutive months.
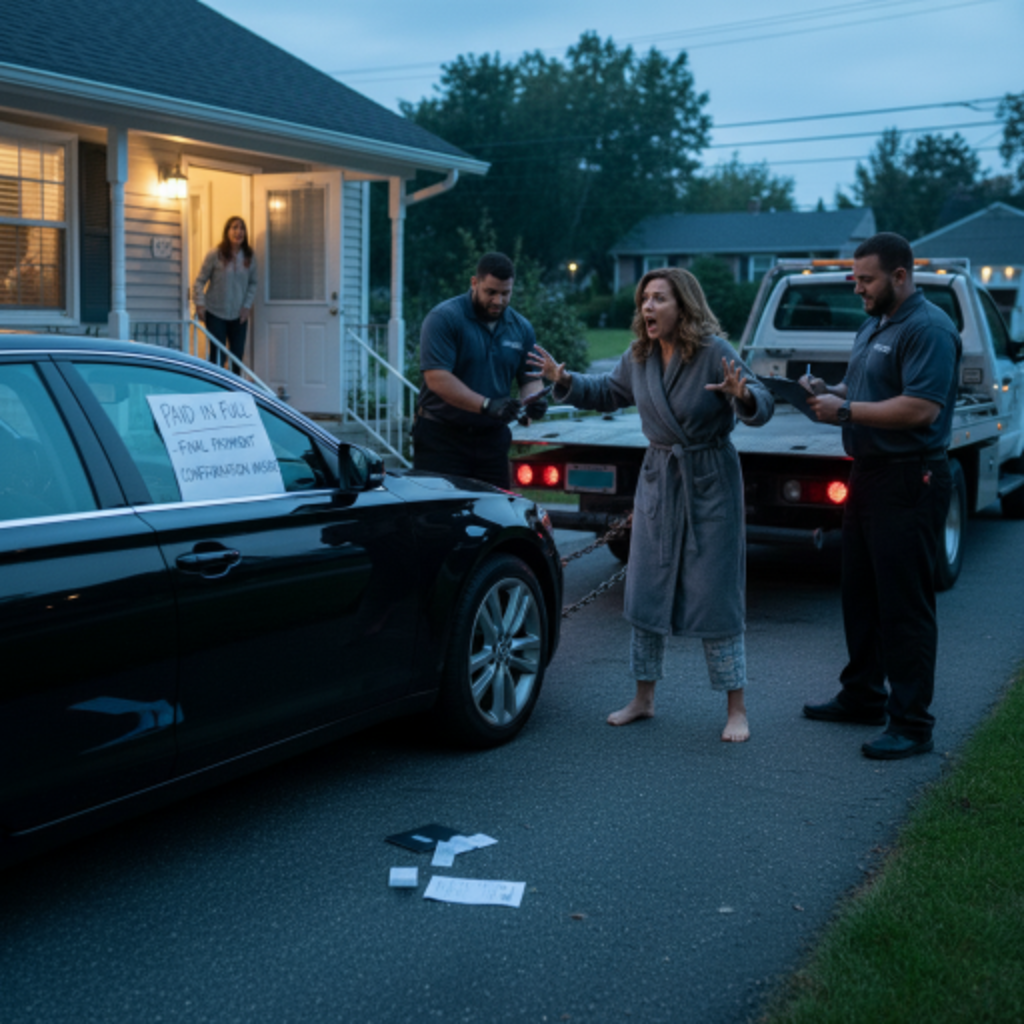
Stop Vehicle Repossession
Auto lenders are strictly prohibited from seizing your car or truck once Chapter 13 is filed. Even if your car was repossessed in the preceding days, your attorney can demand its immediate court-ordered return before title transfers.
Debt Treatment: 100% Priority Debts vs. Discounted Unsecured Debts
A common misconception is that Chapter 13 forces you to repay 100% of all debts. In reality, federal statute establishes a strict hierarchical classification where unsecured debts often receive only a small fraction of their face value.
| Debts Paid at 100% (Priority & Secured Arrears) | Debts Paid at a Fraction (General Unsecured) |
|---|---|
✓ Delinquent Mortgage Arrears Spread over 36-60 months interest-free to keep your primary residence. | ✕ Credit Card Balances Paid pro-rata fraction based on disposable income; remainder discharged forever. |
✓ Domestic Support Obligations Past-due child support and court-mandated spousal alimony must be satisfied in full. | ✕ Hospital & Medical Bills Treated as general unsecured debt; unpaid balance legally wiped out at completion. |
✓ Recent Tax Liabilities (Under 3 Years) Federal and state income taxes that do not meet discharge aging criteria. | ✕ Personal Loans & Signature Notes Payday lenders and peer-to-peer lenders receive fractional dividends with zero ongoing interest. |
✓ Trustee Statutory Administrative Fees Statutory fee percentage approved by the U.S. Trustee Program. | ✕ Repossession Deficiencies & Old Utility Debt Auto loan shortfalls and defaulted utility bills eliminated without full payment. |
For complete classification analysis, read our guide on Texas Non-Dischargeable Debts.
The 11 U.S.C. § 1301 Co-Debtor Stay & Vehicle Cramdown
The Co-Debtor Stay
Unlike Chapter 7 which leaves co-signers exposed to collection lawsuits, Chapter 13 enacts an automatic co-debtor stay. Friends, spouses, and family members who co-signed on personal debts or vehicle notes cannot be sued or harassed so long as your Chapter 13 plan addresses the obligation.
Auto Loan Cramdowns
If your vehicle loan is more than 910 days old, you can cram down your loan balance to the current fair market retail value. Any negative equity balance is stripped away and converted to general unsecured debt, drastically reducing your monthly payment and interest charges.
Advantages & Key Considerations of Texas Chapter 13
✓ Key Advantages
- •Keep All Assets: Shield valuable non-exempt real estate, rental properties, and family heirlooms.
- •Halt Foreclosure & Eviction: Legally forces lenders to accept missed mortgage cure disbursements over time.
- •Broader Discharge Scope: Erases certain obligations not dischargeable under Chapter 7 (like marital property settlements).
- •Protection for Co-Signers: Prevents collection actions against family members who guaranteed your debts.
⚠ Important Considerations
- •3 to 5 Year Commitment: Requires steady, regular monthly payments directly to the bankruptcy trustee.
- •Strict Budgetary Oversight: Incurring new substantial credit or buying a vehicle requires trustee approval.
- •Regular Income Required: You must demonstrate reliable earned income to sustain plan feasibility.
- •Debt Limits: Subject to statutory debt ceilings for secured and unsecured claims under 11 U.S.C. § 109(e).
The 4-Phase Chapter 13 Roadmap
Income Calculation & Plan Formulation
Your attorney evaluates your paystubs, debts, and mortgage statements to formulate a customized, court-compliant Chapter 13 repayment plan and Means Test calculation.
Petition Filing & Automatic Injunction
Filing instantly triggers the 11 U.S.C. § 362 stay, halting foreclosures, lawsuits, and repossession. Your first monthly plan payment is due to the trustee within 30 days of filing.
The 341 Meeting & Confirmation Hearing
Your attorney represents you at the 341 Meeting of Creditors and argues your confirmation hearing before the U.S. Bankruptcy Judge to obtain formal judicial approval of your plan.
Plan Completion & Final Court Discharge
Upon making your final monthly payment, the federal court issues an official Discharge Order permanently releasing all unpaid dischargeable debt, leaving your mortgage current.
Frequently Asked Questions About Chapter 13
How does a Chapter 13 repayment plan work in Texas?+
Under Chapter 13, you propose a court-supervised 3-to-5 year repayment plan to consolidate debt into a single, affordable monthly disbursement made to the Chapter 13 Standing Trustee. The payment amount is based on your disposable income calculated under the Texas Means Test rather than what creditors demand.
Can Chapter 13 stop foreclosure on my Dallas home?+
Yes. The moment your petition is filed, the 11 U.S.C. § 362 automatic stay legally freezes foreclosure proceedings, even if scheduled for a First Tuesday auction hours away. Under 11 U.S.C. § 1322(b)(5), you can cure delinquent mortgage arrears interest-free over 36 to 60 months while continuing your normal monthly mortgage payments.
Can I lower my vehicle payments through a Chapter 13 Cramdown?+
Yes. If your vehicle was purchased more than 910 days (approx. 2.5 years) before filing, Texas Chapter 13 debtors can 'cram down' the loan balance to the fair market value of the vehicle and reduce the interest rate to the court-approved prime rate, often saving thousands of dollars.
What debts must be paid at 100% in a Chapter 13 plan?+
Federal bankruptcy law requires 'priority debts' to be paid in full: domestic child support, spousal maintenance, recent administrative fees, and recent tax debts (under 3 years old). If keeping your mortgaged property, delinquent back arrears must also be brought current through the plan.
What happens to remaining unsecured credit cards and medical bills upon plan completion?+
General unsecured creditors (credit cards, medical bills, personal loans) often receive only a fraction of what they are owed—sometimes as low as pennies on the dollar. Once you complete your 3-to-5 year plan, the federal bankruptcy court enters a final discharge order wiping out 100% of any remaining unpaid unsecured balance forever.